Telecommunications is undergoing a transformation, with new technologies and business models redrawing the landscape. Fifth-generation (5G) wireless communications, cloud computing, decentralized telecom networks, virtualized network services, and AI are among the technologies ushering in innovative services for customers and new business prospects for telecom companies large and small. But while innovation can deliver rewards, it also carries risks. Consider how the IT industry has made inroads into telecom’s traditional turf via the cloud, social media, and collaboration platforms. This article examines how the US telecom market is evolving, tackling challenges, and creating new opportunities.
What Are Telecom Industry Challenges?
Telecom industry challenges are the competitive and technological pressures that shape how telecom companies operate and grow. Most challenges arise from changing market forces, intense competition, and the constant need to expand and update networks.
For instance, as the dominant telecom service providers, giant US mobile and cable operators are using new technologies to ratchet up their battle with each other for market share. At the same time, companies ranging from major cloud providers to systems integrators and smaller network services businesses are expanding their competitive footholds. In the telecom equipment and software markets, meanwhile, established and new suppliers are competing to share in the demand for ongoing network expansion and transformational solutions. Technology-fueled competition represents the predominant dynamic in the telecom industry, promising business growth even as it brings with it myriad challenges.
Key Takeaways
- The telecom industry is undergoing a technology-driven transformation.
- With new technologies come advanced services and more business opportunities.
- In this fast-evolving landscape, challenges have also emerged with regard to market competition, regulation, business performance, and talent management.
Telecom Industry Challenges Explained
For all the opportunities that have come with a telecom industry transformation, enormous challenges have also arisen, including competitive, regulatory, financial, and environmental—as well as technological. For example, the 5G rollout shows how a new technology can reshape how telecom companies compete. Major US telecom companies began rolling out this generation of wireless technology in 2019 to support higher performance expectations from both consumers and businesses. However, some of the most exciting new services that were promised didn’t materialize, leading to the development and implementation of 5G Advanced (5GA), a software upgrade to the network core that allows for more advanced capabilities. Coverage has since expanded, with the United States now achieving over 99% 5G penetration, according to data from Omdia and 5G Americas, compared with the 95% reach in all of North America and 36% global adoption. This growth has made a difference in the following ways:
- New services: 5G delivers faster speeds (with median mobile download speeds of about 300 Mbps, according to speedtest.net’s 2025 awards), lower latency, and greater reliability than previous wireless generations, and its use is growing as a replacement for wireline home and office access as well as mobile broadband. For consumers, this means steadier augmented and virtual reality experiences and more immersive live video streaming. For businesses, applications include industrial equipment diagnostics and remote patient monitoring in healthcare. 5G’s software-defined core also generates real-time data on network conditions, letting AI tools allocate capacity as demand shifts, while edge computing moves data processors closer to customers and connects billions of IoT devices.
- More business opportunities: 5G continues to disrupt the dominant wireless and cable companies’ historical hold on the US telecom market by opening doors for competitive service providers, such as mobile virtual network operators and network-as-a-service (NaaS) providers for enterprises. Small and midsized businesses have also tapped into opportunities created by the 5G and IoT buildout, such as using cloud computing that offers new capabilities without massive infrastructure costs. AI agents are advancing this trend as well, with carriers piloting automated systems that can help smaller teams assemble and manage custom network slices in real time.
26 Challenges Facing the Telecom Industry
Back in the day, telecom companies placed telephone calls, and cable companies delivered TV channels. Over time, digital transformation in business and at home has eroded the profitability of these core services even as it has generated new sources of revenue, including bundles of integrated voice, internet, and entertainment services. Telecom companies need to achieve profitable growth amid technological disruption and related competitive, regulatory, and other challenges.
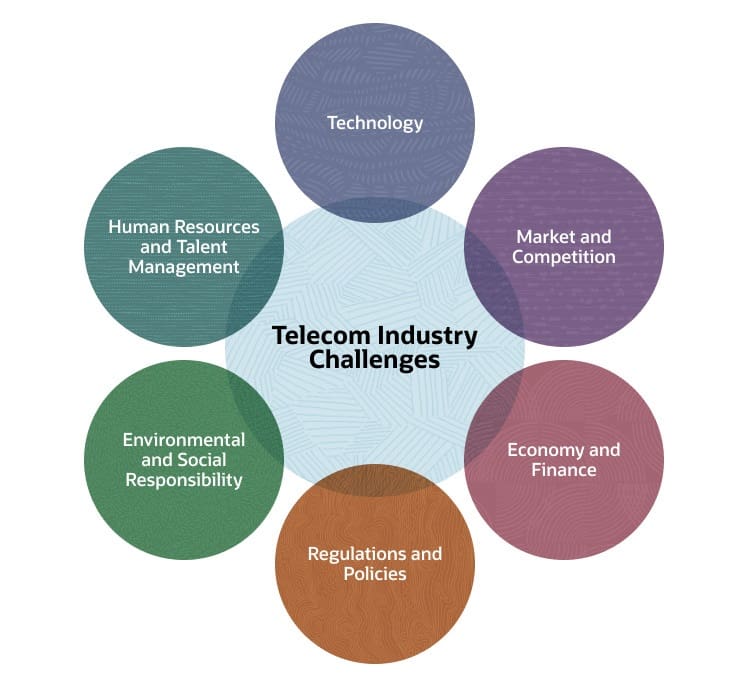
Technology
Recent statistics paint a dramatic picture of accelerating technological change. Americans used 159.3 trillion megabytes of wireless data in 2025, exceeding the entire 4G decade, according to the CTIA’s, “2026 Annual Survey.” At the same time, the number of wireless connections in the nation reached over 600 million, a nearly 15% increase from 2022, including everything from smartphones and smartwatches to environmental sensors and autonomous robots. 5G home broadband subscriptions also rose to a new high of nearly 16 million Americans. Handling all of that traffic isn’t just a matter of speed and capacity, but also complexity, given the variety of devices, increase in service types, and explosion of applications placing unique demands on telecom networks. Technology challenges include:
-
Need for constant upgrades and innovations: The US wireless industry invested nearly $30 billion dollars in 2025 to expand and improve its networks, the CTIA said. In addition to wireless, expensive fiber optic cables provide the backbone for 5G and expand cable companies’ fiber-to-the-home and -office installations at ever-higher speeds. Many telecom companies must take on debt to keep those investments flowing.
-
Investment in research and development: Whether it’s to advance wireless or wireline technology, innovation never ceases. Even before 5G wireless coverage has become available worldwide, equipment vendors have already developed 5GA and have been working on 6G. Meanwhile, wireline networks operated by cable companies are being upgraded to deliver 10 gigabits in both directions, into and out of homes and offices. Even smaller specialists are contributing, advancing niche technologies like virtual SIMs and energy-efficient wireless links. Amid all this innovation, the big challenge for the dominant telecom service providers is that they’ve largely ceded R&D leadership to equipment makers, software companies, and cloud providers. Experts say this makes it hard for them to competitively differentiate themselves.
-
5G implementation and development: Even with widespread 5G coverage, newer consumer applications like widescale virtual reality, as well as business use cases, such as private networks for highly automated factories, have had less consistent adoption. 5GA network software upgrades are changing that through expanded capabilities, including ultra-low latency and dynamic network slicing, that newer applications need. Network operators are extending 5GA’s reach with Reduced Capability devices, such as smartwatches, that need only lower-power IoT connections, along with non-terrestrial networks, such as satellite connectivity, that bring more reliable coverage to remote areas. The next phase of standards is expected to deepen AI-driven network automation and improve energy efficiency.
-
IoT and connected devices: IoT devices, which add remote sensing and other capabilities in US supply chains, electricity grids, and security surveillance systems, already number in the billions—and counting. For all those devices, services and connectivity represent a substantial share of enterprise IoT spending, with telecom companies, systems integrators, cloud providers, and others all vying to provide the required design, connectivity, data management, and analytics for businesses. Big telecom companies have been driven to partner with competitors to handle the sheer scale and complexity of implementing IoT.
-
AI and machine learning applications: Like other technologies, AI and machine learning present telecom companies with both opportunities and challenges. For instance, AI can improve network operations, customer support, and service offerings. Machine learning, meanwhile, can optimize network performance, predict and prevent outages, and perform predictive maintenance. At the same time, however, telecom companies need to overcome the challenges presented by AI and machine learning, such as integrating them into legacy systems even while the skills to do so are in short supply.
-
Increasing prevalence of cyberattacks: Telecom networks represent critical infrastructure that’s subject to cyberattacks from hostile nations as well as cybercrime syndicates. As cyberattacks on all types of companies continue to multiply, telecom companies’ increasingly complex digital environments, multiplying access points, and growing stores of customer data make them more vulnerable and more attractive to cyberattackers than ever. Smaller telecom companies may be particularly vulnerable to network security threats, because they lack the resources of their larger peers to deflect them.
-
Maintaining network reliability: Despite network upgrades, about one in four households still often experience unreliable fixed broadband connectivity, though that figure has started to improve—it’s down from 26% to 24% year-over-year, according to an EY study. 5GA and AI upgrades aim to further strengthen performance management as these technologies mature and are more widely implemented.
Market and Competition
The US telecom market is enormous, with hundreds of billions of dollars in annual revenue. Competitors continually emerge to reach for nearly every slice of that pie. On one level, social media messaging and collaboration and conferencing platforms have eroded dominant telecom companies’ text and voice revenue. On another level, telecom equipment providers, systems integrators, and managed service providers compete with the leading telecom companies to sell private networks to enterprise customers. Cloud service providers, meanwhile, represent the prime example of what’s called over-the-top services. These represent a significant drain on telecom network traffic and revenue because they deliver services via the internet with minimal to no involvement of a telecom operator. Meanwhile, mobile and cable companies aggressively compete against each other in these and other services markets. Competitive challenges include:
-
Intense competition leading to reduced profit margins: Telecom companies’ net profit margins tend to run in the high single digits to low double digits, which is far below average IT sector margins but still considered healthy. Intense competition is among the main factors keeping profits at this level—and sometimes lower, as is the case when major wireless operators and cable companies get into price wars.
-
Struggle for market share among industry giants: The major US wireless and cable companies compete with each other by bundling broadband Internet access, TV channels, streaming services, and mobile and landline voice services. They cross over into each other’s markets in various ways. Among them, wireless companies are building 5G fixed wireless access connections into homes, while cable companies buy wholesale wireless capacity and resell services to their customers as mobile virtual network operators. Meanwhile, organizations like NTCA–The Rural Broadband Association, which represents about 850 independent US telecom companies, and America’s Communications Association (ACA Connects), which represents approximately 500 independent operators, work to help these smaller providers compete with larger enterprises, including through partner programs that support bundled offerings in lesser-served areas.
-
The emergence of over-the-top (OTT) services: OTT services—streaming channels, messaging apps, online conferencing—erode telecom revenue. Running “over the top” of the telecom network, they compete directly with telecom companies’ own voice and video products. This has created a “frenemy” relationship with hyperscalers, such as Amazon, Google, and Microsoft. Telecom companies compete with these hyperscalers, which deliver many OTT services. At the same time, telecom companies are also massive customers of hyperscalers, migrating their own internal IT and network functions to the cloud.
-
The importance of quality customer service: Intense competition increases the need for telecom companies to provide a positive customer experience, which has not historically been their strong suit. What’s more, the seamless online experiences of digital-first brands have heightened customer expectations and forced telecom companies to redefine their customer relationship management. Customer experience is one of the primary ways that telecom companies differentiate themselves, especially as connectivity becomes more commoditized and margins tighten. To achieve this, companies are turning to AI, such as generative AI chatbots trained on the company’s actual service data, that can speed up service call routing and offer more robust self-service troubleshooting options.
-
Shifting consumer preferences: In the consumer market, the home often doubles as the workplace. The home might be a smart home, with devices for automated security, energy, and cleaning. At the same time, various members of the household could be using increasingly sophisticated digital devices and services for entertainment, healthcare, and education. Telecom companies are delivering higher-speed broadband services to fulfill all this demand, as well as wireless routers, phones, tablets, watches, and even smart vacuum cleaners, thermostats, and security cameras. While telecom companies are considered to be well-positioned to cater to the smart-home market, many of the devices still aren’t entirely DIY, requiring more customer interaction than telecom companies typically engage in.
-
Rising customer expectations and demands: Business customers’ need for NaaS poses another set of challenges. For example, many telecom and IT companies are pursuing private networks as a growing market, especially those with shrinking margins for other product lines. New telecom technologies, such as network slicing, are coming online to combine customized “slices” of telecom network resources for computing, storing, and networking to meet specific business needs. Nevertheless, competition for conventional private networking is already intense among traditional telecom companies, network equipment providers, specialized network service providers, systems integrators, and others. And no single type of provider is seen to be strong in all the areas in which businesses need solutions.
-
Handling customer churn: Telecom customer retention rates are low compared to other industries. In fact, various sources cite annual churn rates in the low double-digits, depending on type of service and payment arrangements. Subscribers churn for a number of reasons, including poor customer service, competitive offers, billing issues, and network reliability issues.
Economy and Finance
When the economy is uncertain, telecom companies must overcome several economic and financial challenges to their profitability and growth. In this capital-intensive industry, for instance, network operators currently face higher interest rates on their significant levels of debt. But even if there’s an economic downturn, people and businesses still need to connect, which guarantees a certain level of recurring revenue. Other economic and financial challenges include:
-
High capital expenditure for infrastructure development: The competitive race to build out 5G infrastructure has abated, though software and cloud service upgrades to the 5GA core network are in progress to deliver advanced capabilities and services. But the capital intensity of telecom remains higher than in most other industries, due to the heavy infrastructure burden. With high CapEx (capital expenditures) comes high debt levels and interest payments. Meanwhile, for smaller telecom companies, the high cost of telecom equipment presents a challenging business case and even a barrier to market entry. But virtualized network services, such as NaaS, can provide a less capital-intensive alternative.
-
Financial sustainability and profitability concerns: To cover their high costs, major telecom companies often need to make operations more efficient and monetize their 5G and fiber investments by developing new products and services. But build and expand too fast, and customers may not arrive fast enough to recoup the costs before obligations come due. As for current services and ongoing price wars, telecom companies have less and less pricing power as connectivity and data services become increasingly commoditized. They’ve also seen their costs driven higher by inflation, eroding profitability.
-
Impact of economic downturns on the telecom industry: For all its challenges, the telecom industry has advantages that could help shield it from the impacts of an economic downturn. One such advantage, as mentioned above, is that consumers prioritize connectivity, providing steady revenue despite price increases. That said, telecom companies face significant pressure from shifting tariffs and other geopolitical rifts, which can increase their regulatory burden and input costs.
Regulation and Policies
Telecom is a highly regulated industry, and policymakers’ priorities shift in line with economic, political, and societal changes. For example, cybercrime, geopolitical conflict, and a cost-of-living crisis have brought greater regulatory oversight of network security, network supply chains, and the digital divide between those who have access to broadband and those who don’t. Also at the top of the agenda is spectrum availability and how regulators will make more airwaves available for continued wireless expansion and innovation. More specifically, regulatory challenges include:
-
Highly regulated environment: Regulation is a double-edged sword. Policies can accelerate innovation with subsidies and radio spectrum, as they have with 5G, but regulation can also inhibit innovation in other areas as it limits big industry players from experimenting with new business models. Regulatory shifts can drive up compliance costs and complicate expansion efforts, especially when rules change after a strategic pivot has already started. Smaller providers typically bear the brunt of these pressures since they often lack the dedicated legal and regulatory teams that their larger competitors keep on staff, but automated and AI-assisted compliance tools can help keep companies up to date.
-
Meeting varied regulatory standards: The range of telecom regulations is wide—from requiring US telecom companies to replace Chinese equipment in their networks to demanding new broadband labeling that helps consumers better understand their service options. Other varied areas of regulation cover spam texts, rural broadband service, subsidies for Wi-Fi on school buses, and net neutrality, the latter of which embodies the principle that telecom companies must treat all data on the internet the same way and not discriminate or charge differently based on user, content, website, or application. Beyond Washington, some regulations that originate abroad become ad hoc global standards, such as data privacy rules or Europe’s AI Act. And for telecom companies operating in different countries, diverging regulations and technical specifications can complicate market entry, regulatory compliance, and operational efficiency.
-
Handling user data and privacy concerns: Telecom companies handle an extraordinary volume of data on customers, including standard personal identification information, payment data, their real-time location, and the very content being transmitted. Providers use some customer data (though not the content) for marketing insights and product development. And, as allowed by the FCC, they also sell certain types of anonymized customer data to enterprises looking to analyze consumer behavior so they can target ads. Customers can go online and opt out/opt in to some of these programs. But telecom companies’ handling of data privacy is often a hot-button issue with consumers and privacy advocates, especially following cybersecurity breaches involving customer data. Although the United States doesn’t have an overarching national data privacy policy, various state and federal agencies cover aspects of consumer data. Also, Europe’s General Data Privacy Regulation, which includes hefty fines for noncompliance, set the global standard in 2018 and provides the model for state data privacy laws, such as the California Consumer Privacy Act.
Environmental and Social Responsibility
The telecom industry has work to do on environmental and social responsibility. EY ranked poor management of the sustainability agenda as the industry’s ninth-biggest risk for 2026, noting that even though 75% of participating operators reported lower Scope 1 and 2 emissions, “60% of telco leaders are rethinking the timelines for their sustainability commitments.” Social responsibility remains a weak spot too: Only two telecom companies cracked the top 50 in Newsweek’s “America’s Most Responsible Companies 2026” list. Some of the challenges facing telecom companies in this area are:
-
Implementation of green technologies: 5G is touted by the industry as an inherently greener technology, but the debate is far from settled. On one hand, 5G can reduce energy consumption and waste in some industrial applications, such as supply chain monitoring that tracks shipment conditions and goods in real-time to minimize spoilage and keep transportation efficient. Telecom operators are now applying that efficiency push to network operations directly through AI-powered network management and usage monitoring. On the other hand, 5G networks still require a dense web of energy-consuming antennas, and the AI workloads embedded in network operations are driving up power demand. And as data use continues to rise, these factors keep adding to the industry’s overall energy costs.
-
Waste management and reduction strategies: E-waste is the world’s fastest growing waste stream and one of the telecom industry’s biggest waste-management challenges. Verizon reported reusing or recycling over 92 million pounds of materials in 2024, including cellphones, chargers, set-top boxes, network equipment, batteries, and plastic components. According to STL Partners consultancy, tackling the e-waste challenge will take significant partnerships to set and achieve ambitious goals for recycling, reusing, and championing the use of longer-lasting equipment within supply chains.
-
Bridging the digital divide: A shrinking but persistent share of US households still lack internet access—around 4.5% of households, or just over 6 million, according to the most current Census data. Rural telecom often lags behind the rest of the country when it comes to the implementation of broadband, due to the high cost of covering sparse populations with wireline networks, and 5G aims to ease that burden. To further decrease the divide, the $42.45 billion Broadband Equity, Access, and Deployment program, originally authorized in 2021 and revised in 2025, is now moving into construction.
-
Ethical considerations in technology deployment and service provision: As telecom companies expand their use of AI and customer data, including GenAI chatbots and AI-driven network management, new accountability considerations and clear governance become essential. When the governance team doesn’t clearly assign ownership, it’s not always obvious who’s accountable when something goes wrong. And when a company has loose data control processes, customer information becomes vulnerable, especially when the company has complex vendor and technology partnerships. AI systems in particular need regular testing, not just an initial rollout check, to catch issues and model drift before they reach customers.
Human Resources and Talent Management
The telecom industry needs to strike a balance between profitability and employee welfare, with many moving parts on both sides of the equation. Talent challenges facing telecom companies include:
-
Need for a skilled workforce in evolving technologies: Telecom companies face a skills shortage that hinders the development and implementation of emerging technologies and innovative business models. This challenge persists, in spite of layoffs in both the telecom equipment and services sectors. Sought-after skills tend to be on the cutting edge of technologies, such as big data and AI, while other jobs are on the cutting block as automation replaces back-office workers in customer service.
-
Keeping employees satisfied and motivated: When it comes to employee retention, telecom companies sit just below the global average on employee engagement, according to the July 2026 telecommunications report by Culture Amp, an employee experience platform company. That means that 70% of telecom employees are engaged, emotionally committed to their organization, likely to stay longer, and apt to be more productive and effective, compared to the global median of 71%. Higher satisfaction means employees are less likely to seek employment elsewhere, lowering onboarding and training costs.
How Telecom Companies Can Mitigate Challenges and Risks
Mitigating challenges and risks requires a multifaceted strategy for simplifying operations, updating infrastructure, and diversifying revenue while reinforcing security, sustainability, and workforce skills. Telecom companies can follow these best practices:
- Identify automation opportunities: Providers should begin by targeting repetitive, high-volume tasks, such as billing, service provisioning, and network diagnostics, for automation. This step can serve as a catalyst for larger digital transformations.
- Prioritize technology that will update and enhance services: Priority technologies today include AI-driven network management as telecom companies upgrade to 5GA, finally delivering long-promised services, such as network slicing for businesses and virtual reality for consumers.
- Consider new revenue streams: Telecom companies need to develop and scale new business-to-business digital services in areas like IoT, private 5G networks, and edge computing. These are areas they’ve often ceded to competitors.
- Shore up cybersecurity and compliance protocols: Cybersecurity risk is a double-edged sword. On one side, bad actors are constantly trying to break into telecom networks. On the other, regulators threaten penalties for weak security and personal data privacy.
- Embed sustainability goals into new infrastructure: Many telecom companies are stepping up their sustainability efforts by decommissioning legacy copper networks to cut energy consumption and by introducing newer network technologies, including fiber and 5GA, that use less energy than the infrastructure they replace. The core network needs to operate efficiently, too, so many companies are relying on AI to move from static, always-on networks to ones that dynamically manage power and resources based on real-time traffic.
- Cross-train and upskill workforce: Telecom companies’ need for re-skilling and fresh talent remains a pressing concern, particularly as companies in nearly every industry now compete for the same AI and software talent that used to be more focused in telecom and IT. Many telecom companies are also accustomed to designing fixed assets built to function for decades, and the pivot to software and cloud development cycles can be challenging, especially when the back-office updates and legacy system overhauls necessary to stay competitive now take weeks of rapid deployment instead of months of careful planning.
Manage Your Telecom Challenges With NetSuite ERP
Small and midsize companies in the telecom sector can step up to industry opportunities and challenges using ERP systems with integrated software for financial management, CRM, and human resources. In particular, NetSuite Telecom ERP can help telecom companies provide seamless customer experiences across products and services, ease consolidation of financial data, and manage multiple subsidiaries efficiently. Specific benefits of a NetSuite ERP implementation for a telecom company include support for diversification of services through billing, the handling of customer relationships in call center environments, and management of new and existing employees.
NetSuite Telecom ERP

The telecom industry’s technology-fueled transformation is elevating the level of competition for existing and emerging services. To succeed, telecom players, large and small, must overcome a host of challenges in mastering new technologies, besting the competition, navigating regulatory requirements, rising to new mandates for environmental and social responsibility, and attracting and retaining the necessary talent.
Telecom Industry Challenges FAQs
What are the challenges of the telecommunications industry?
The telecom industry has been characterized by very high capital expenses, stiff competition, and uncertain growth in recent years, dampening telecom companies’ business performance.
What’s the biggest challenge facing the rural telecommunications industry?
Rural communities often lag behind the rest of the country when it comes to broadband implementation because of the high cost of covering sparse populations with wireline networks. 5G holds the promise to bridge that divide with its ability to provide fixed wireless access to homes.
Why is the telecom industry so competitive?
The telecom industry involves many competitors, large and small, as the result of technological convergence in areas such as voice, internet, and entertainment services, as well as the kinds of cloud computing and edge networking capabilities needed for the Internet of Things and other services considered the future of the industry.
What are the risks of telecommunication?
The telecom industry faces many challenges—technological, competitive, regulatory, financial, and environmental. The telecom industry is a capital-intensive business in which competition, macroeconomic pressures, and uncertain demand for new services have combined with shifting regulatory requirements and new environmental mandates to elevate business risk.