Insurers succeed or fail on their understanding of risk and their ability to price it correctly. In 2026, that’s become harder than it’s been in years. The obvious threats still matter, but the ones that are tougher to see are quietly reshaping the business: a generation that views million-dollar verdicts as fair; a trade dispute that inflates auto claims; a talent shortage that hits just as the work grows more complex.
This article surveys nine trends that are changing insurance this year, examining what each means for executives, agents, brokers, claims managers, and operations teams trying to price and manage risk.
Key Takeaways
- “Social inflation” is driving up claims costs—the median “nuclear verdict” against corporations reached $51 million in 2024, more than double the 2020 median.
- AI has moved past experimentation into everyday underwriting and claims work, and it touches nearly every other trend. Its value, though, varies from company to company because it depends on clean, connected data.
- Geopolitical conflict has become a direct pricing force.
- Climate-driven catastrophe losses have topped $100 billion for six straight years, forcing carriers to rethink how they price and place risk.
- A retirement wave is draining experience from the industry.
The Forces That Are Driving the Insurance Landscape
A handful of forces sit behind almost every trend described below. Climate volatility is pushing losses higher and making them harder to predict. Legal and social pressure is inflating the cost of claims. Technology—AI above all—is rewiring how carriers price risk and handle claims. And economic and geopolitical uncertainty, whether the result of interest rates, trade policy, or open conflict, is squeezing both sides of insurers’ balance sheets. Add a workforce that’s rapidly aging, and you get an industry changing in both character and substance.
9 Major Insurance Industry Trends of 2026
These are the nine most important trends confronting insurance companies this year, ranked by impact from those already affecting the business to the ones just emerging.
-
Climate Resilience and Climate Risk Management
Natural catastrophes have generated more than $100 billion in insured losses for six years running. Now, though, losses are more frequently coming from secondary perils, such as wildfire and flooding, instead of the major hurricanes that carriers built their models around. A large share of at-risk property still carries no coverage at all, and that widening protection gap is pushing carriers to rethink catastrophe pricing and, in the hardest-hit regions, whether to write coverage there at all. Reinsurance offers some relief. After the steep price hikes of 2022 and 2023, capital has poured back in and catastrophe reinsurance rates dropped sharply at the start of 2026, easing some of the pressure on primary carriers.
-
Social Inflation
Social inflation refers to the rising cost of claims driven by factors beyond ordinary economic inflation. It comes mainly from litigation and a trend toward larger jury awards, and its clearest signal is the escalation of the “nuclear verdict”—awards of $10 million or more. The median nuclear verdict against a corporation was $51 million in 2024, more than double its 2020 level. The usual explanation blames plaintiff attorneys and litigation funding, but Swiss Re’s research points to something harder to price, the fact that younger adults are far more likely than older ones to see big awards as fair. As younger people fill more jury boxes, large payouts have become the expectation, rather than the exception. That pressure is already showing up in liability lines, such as commercial auto, where premium rates have been rising for years.
-
Monitoring Global Uncertainty
Economic and geopolitical volatility moved from background noise to a direct pricing force in 2026. Take tariffs, where higher costs on imported auto parts, for example, have pushed up repair bills and claim severity for commercial auto insurers. Conflict is the bigger shock, as war and political violence claims continue to rise. The pressure lands hardest on a few lines, mainly US casualty, commercial auto, and war coverage, where litigation, repair costs, and reduced capacity due to supply chain disruption in contested regions keep forcing up rates.
-
Increasing Demand for Cyber Coverage
Demand for cyber coverage keeps growing as ransomware and data breaches hit businesses of every size. Munich Re expects the global cyber insurance market to more than double by 2030. Even so, it remains a small slice of the overall property and casualty market, which shows how much room it has left to grow. The hard part for insurers is modeling a risk that shifts as fast as the threats do, since a single attack on a popular software vendor can trigger claims from thousands of policyholders at once. That’s pushing carriers toward machine learning models trained on live threat data so they can reprice risk as it reinvents itself month to month.
-
Hiring and Retaining Younger Talent
The insurance workforce is aging. A wave of retirements is escorting decades of underwriting and claims expertise out the door, and carriers are struggling to fill critical specialty roles that normally take years to develop, such as catastrophe underwriters and cyber-risk specialists. The hiring picture isn’t all grim, though, since most insurers plan to maintain or grow their head count in 2026. The challenge lies in the competition for younger, tech-fluent workers who rarely put insurance at the top of their career list. That puts a premium on adopting sharper recruiting approaches.
-
Increasing Regulations
Insurers are coping with heavier compliance demands on three fronts at once—namely, new climate disclosure rules, a growing patchwork of state privacy laws, and closer scrutiny of how they use AI. In fact, the National Association of Insurance Commissioners has issued a model bulletin regarding AI that roughly half of US states have adopted or echoed. Maintaining compliance is expensive, because each new requirement means more staff time and new reporting systems. The burden multiplies for carriers that write business in many states, since a rule in one state rarely matches the rule in the next. That drag pulls people and budget away from underwriting and growth, which is a big reason insurers are turning to regulatory compliance tools that automate tracking and reporting.
-
Personalized Products
Customers increasingly expect insurance that fits how they actually live and work, which is fueling usage-based auto policies priced according to real driving data and embedded coverage sold at the point of purchase, like travel insurance offered during checkout for an airline ticket. On the commercial side, the same appetite is fueling growth in parametric policies that pay out automatically when a trigger event occurs, such as a hurricane. It’s also spurring the growth of captive insurers that let larger businesses self-insure hard-to-place risks. AI makes it all work by turning behavioral and sensor data into individualized quotes. For agents and brokers, the trend means selling through new channels and partners, instead of the traditional renewal call.
-
Underwriting Innovation
Underwriting is shifting away from a manual, document-heavy process toward real-time analysis. Carriers now draw data from sources, such as telematics and satellite imagery, to price risk more precisely, and they use AI to spot submissions that need a human expert’s attention. A corollary change is what the industry calls continuous underwriting. Instead of assessing a risk once at renewal, carriers monitor it throughout the policy term and adjust as conditions change. Purpose-built insurance ERP systems tie that risk data to the organization’s accounting and finance systems.
-
Digital Transformation and AI
AI has moved from pilot projects into the daily work of underwriting and claims. Generative AI can read unstructured documents, such as adjuster notes and medical records, then draft summaries a person can review and approve. AI agents do more. They monitor conditions and carry out multistep tasks within set permissions, as part of a broader digital transformation of the way carriers operate. The catch is that these tools rely on clean, connected data, yet many insurers still run on older systems that keep information walled off department by department.
ERP Software Helps Insurance Agencies Stay Ahead of the Curve
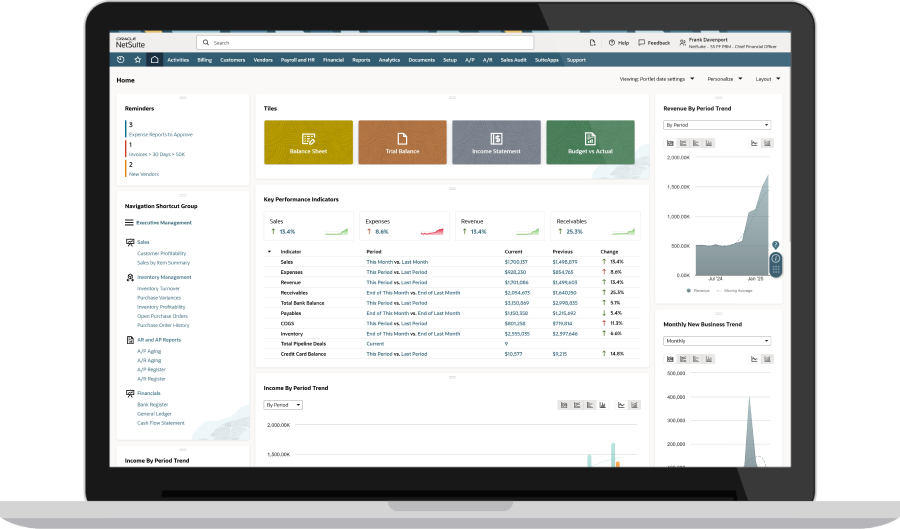
These nine trends share a common thread: They all demand fast, trustworthy data, which is hard to produce when information is scattered among disconnected systems. NetSuite Insurance ERP brings finance, operations, and reporting into one platform, so the numbers behind a pricing decision or a regulatory filing come from the same place the rest of the business runs on. The Ask Oracle conversational AI interface lets teams query that data in plain language, then returns answers with source citations teams can check. AI-powered anomaly detection scans financial data for unusual patterns and recommends corrective action, and AI agents can monitor routine processes and handle exceptions within a company’s own approval rules. For insurers encountering rising claims costs and tighter regulation, that connected foundation helps turn raw data into decisions faster.
Simplify Cross-Department Workflows With NetSuite Insurance ERP
No single trend defines insurance in 2026. Climate volatility, social inflation, geopolitical shocks, and rapidly advancing AI are all poking at the business, yet each one rewards the same thing—the ability to see clearly and act fast. The insurers that come out ahead will be those whose data and systems help them move as fast as the market does.
Insurance Industry Trends FAQs
What are the latest trends in insurance?
The biggest trends shaping insurance in 2026 include rising social inflation and larger jury verdicts, geopolitical conflict and trade volatility, climate-driven catastrophe losses, and growing demand for cyber coverage. Tighter AI regulation, an aging workforce, and the spread of AI in underwriting and claims round out the list.
Why does social inflation matter to insurers?
Social inflation raises the cost of claims faster than ordinary inflation would, mostly through larger jury awards and more aggressive litigation. This erodes profitability in liability lines and pushes insurers to raise premiums or pull back coverage, which, in turn, affects the businesses and individuals who depend on that coverage.