Winning new policyholders may start with competitive pricing, but retaining a customer’s business for the long run often depends on the quality of their experience. That, in turn, usually depends on how smoothly the insurance back office runs. But insurers are dealing with a variety of challenges—constantly changing regulations, talent shortages, customer expectations for faster digital service, and complex market forces—prompting many to revamp how work gets done behind the scenes.
This guide explores the critical role of the back office, the challenges it faces, and the strategies insurers are using to improve productivity, control costs, and deliver a top-notch customer experience.
What Is the Insurance Back Office?
The insurance back office refers to the administrative and operational functions performed by employees who support the company’s day-to-day business but don’t interact with customers.
The unseen work of back-office teams is critical to insurers’ success. They handle a wide variety of tasks, including making sure policies are issued correctly, claims are processed accurately, regulatory requirements are met, and customer-facing employees have the information they need to respond quickly to the questions and concerns of policyholders.
Key Takeaways
- Back-office teams help insurance companies run smoothly by processing policies and claims quickly and supporting frontline employees in providing speedy, high-quality customer service.
- A major storm, regulatory change, or enrollment period can overwhelm insurers overnight, so scalability is one of the back office’s most valuable strengths.
- Legacy systems, disconnected data, and growing pressure to do more with fewer resources are some of the factors driving insurers to modernize their back offices.
- Insurers can build a more efficient back office by automating high-volume tasks, standardizing workflows, and upgrading their software.
- Insurers can boost premium growth and sales conversion rates by redesigning business functions to use AI.
Insurance Back Office Explained
The pressure on back-office operations has intensified in recent years. Extreme weather events are spurring costlier and more complex claims, regulators are introducing new reporting and compliance requirements, and many insurance companies are bemoaning an aging workforce and difficulty recruiting skilled employees. At the same time, customers expect companies to process new policies and claims within days—or even hours—not weeks, and they are seeking digital, self-service experiences similar to those offered by banks and retailers.
As a result, many insurers are reevaluating their back-office processes in a quest for greater efficiency. That is leading them to a variety of new approaches, such as outsourcing routine administrative tasks and investing in technologies that help employees manage growing workloads, designed to accelerate processing and improve accuracy.
Key Functions of the Insurance Back Office
The back office spans the entire life of a policy, from vetting an applicant before coverage is written to paying out when a claim lands, plus all the in-between finance and compliance work that keeps the operation running. Five broad functions handle most of that load:
- Underwriting support: Underwriters rely on back-office staff to gather applicant information, verify documents, order inspections and medical records, and prepare risk assessments. By handling these tasks, support teams help underwriters focus on the important responsibilities of evaluating risks and making pricing decisions.
- Policy administration: Every insurance policy requires a steady stream of administrative work, including processing endorsements, updating customer information, and reworking or renewing coverage. Solid policy administration is important for minimizing errors and delivering a quick turnaround for customers.
- Claims processing: Claims teams verify coverage, investigate losses, detect potential fraud, and coordinate payments, whether they’re handling an auto collision, a homeowner’s claim after a storm, or a health insurance reimbursement. Because claims can be an emotional “moment of truth” for policyholders, faster and more accurate processing can both improve customer satisfaction and trim operating costs.
- Finance and accounting: Insurance companies process thousands, perhaps millions, of financial transactions each year as they collect premiums, pay claims, reconcile accounts, and prepare financial reports. Finance teams must make sure payments are accurate, reserves are properly tracked, and financial records meet regulatory and accounting standards.
- Compliance management: Insurance is among the most heavily regulated industries in the world, with state and federal laws that are constantly evolving. Back-office compliance teams must monitor regulatory changes and prepare for audits, so insurers can escape costly penalties.
Why Are Insurance Agencies Modernizing Their Back Offices?
For many insurers, the back office still relies on decades-old technology and disconnected processes. Employees often toggle between multiple systems to complete a single task, forcing them to manually re-enter information and waste valuable time on routine administrative work. These inefficiencies not only slow the processing of policies and claims but also increase operational costs, introduce errors, and make it tougher for agencies to respond quickly to customer requests.
Consequently, many insurers are redesigning how work flows through their organization, recognizing that digitization, automation, and technological modernization have become vital to boosting productivity and creating value. Nearly 4 out of 5 executives from 245 insurance companies surveyed by Accenture in 2025 said those three capabilities are significantly more important today than they were just three to five years ago.
Legacy Challenges Impacting Insurance Back Offices
Insurance back offices face several obstacles that can increase costs, delay claims, and make it harder to deliver high-quality service. Insurer's main legacy challenges are:
- Data silos: According to a 2025 survey, 66% of insurance firms are juggling more than 10 data sources to complete premium payments. Data silos created by multiple systems that don’t communicate well with one another force employees to search several databases to complete simple transactions, such as confirming policy details, reviewing claims histories, or processing endorsements. They waste time and increase the risk of errors.
- Poor scalability: Without the ability to scale processes quickly, insurers struggle to keep up with sudden spikes in claims. They find themselves overwhelmed after a hurricane, wildfire, or other serious event that causes major damage. This can lead to backlogs that persist for weeks or months.
- Repetitive manual processes: Many insurance employees are still entering the same information into multiple systems, reviewing documents by hand, or manually moving files from one department to another. Besides slowing productivity and increasing operating costs, these manual workflows can cause delays in issuing policies and processing claims.
- Evolving regulatory landscape: In the United States, insurance is regulated primarily at the state level, creating a patchwork of licensing, reporting, privacy, and consumer protection requirements. As regulations change, particularly when related to cybersecurity and data privacy, back-office teams often find themselves scrambling to update their processes to remain compliant.
- Talent gaps: The US insurance industry faces a shrinking pool of talent—and, as experienced employees retire, decades of institutional knowledge and field judgment leave with them. In fact, a 2025 Deloitte report found an average attrition rate of 20% among chief claims officers of leading property and casualty insurers, and each exit resulted in the loss of nearly six years of experience.
Software and Technology Modernizing Insurance Back Offices
To overcome the obstacles of their legacy challenges, many insurance companies are turning to the following technologies.
Predictive Analytics
Insurance companies are beginning to deploy machine learning (ML) models that have been trained on historical claims, policyholder behavior, and third-party data to predict outcomes that traditional reporting can’t foresee, such as claims frequency, fraud probability, churn likelihood, and loss exposure after catastrophic events. Predictive modeling provides answers to those conjectures by analyzing patterns humans often miss. When it comes to churn, for example, ML models can detect subtle signals that precede cancellation—a spike in billing inquiries, a missed payment, a negative service interaction. For catastrophe planning, predictive models now incorporate satellite imagery and real-time weather feeds to estimate regional loss exposure before a storm makes landfall, allowing insurers to deploy adjusters where demand is expected to be highest. The result is earlier intervention, sharper resource allocation, and underwriting decisions grounded in pattern recognition instead of averages.
AI and Agentic AI
AI helps automate mundane, repetitive administrative tasks—such as extracting data from submitted documents, answering routine policyholder questions, and transferring information among systems—easing the burden on both frontline and back-office staff. Agentic AI takes things a step further by reasoning through entire workflows instead of stalling on exceptions. In claims processing, for instance, an agentic workflow can check submitted photos against weather data, validate policy coverage dates, request a missing contractor invoice via email, score fraud probability, and either approve the claim automatically or route it to an adjuster with a complete case summary—all within minutes and logged for compliance. The technology is leading to measurable gains: Insurers using AI to redesign specific business functions are achieving up to a 40% reduction in customer onboarding costs, 10% to 15% premium growth, and a 10% to 20% improvement in new-agent success and sales conversion rates, according to a 2025 McKinsey report.
Intelligent Document Processing
Insurance companies must carefully review every application, police report, repair estimate, medical record, provider invoice, and proof-of-loss form, which makes insurance one of the most document-intensive industries. Instead of requiring employees to enter information manually from dozens of forms, intelligent document processing combines optical character recognition with AI to extract information from documents, such as policy numbers, accident dates, vehicle information, and claimant details. AI agents can then classify the data and send the information through the system in seconds, cutting down on both processing time and data entry errors.
Workflow Automation
A single insurance document touches a lot of hands as it passes through customer service representatives, adjusters, fraud investigators, lawyers, medical reviewers, and finance teams. Workflow automation can propel documents through back-office functions at a rapid pace. By replacing manual handoffs with rule-based and AI-powered processes, workflow automation can route tasks to the appropriate employee, request missing information, send status updates, and escalate policies or claims that need additional review. For example, a low-risk auto claim with complete documentation can be routed directly to an adjuster, while a potentially fraudulent claim can be tagged for more thorough investigation. Managers also gain real-time visibility into workloads and bottlenecks, enabling them to rebalance resources before slowdowns occur.
Cloud-native Software
When a hurricane, wildfire, or cyberattack suddenly generates thousands of claims, legacy on-premises systems may struggle to keep up, slowing processing exactly when policyholders are desperate for help. Cloud-native platforms allow insurers to scale computing power as demand increases, so claims can continue to flow even during major catastrophic events. Cloud software also makes it easier to connect with third-party data providers, such as weather services, repair networks, medical providers, and fraud databases, and gives employees secure access to policy and claims information. Plus, cloud platforms don’t require lengthy maintenance windows as traditional software does—software updates and security patches occur faster and with less disruption to daily operations.
ERP Systems
The enormous data volume that insurance companies generate is frequently scattered among the separate systems used by finance, claims, procurement, compliance, and other departments, complicating business leaders’ ability to get a clear, overall picture of their operations. ERP software for the insurance sector unites functions on a single platform, so information entered in one department is immediately available to the others, as well. This gives insurers a single source of truth they can rely on to manage finances, allocate resources, monitor performance, and speed up decisions. For example, after a major storm, managers can quickly see how many claims have been filed, whether enough adjusters are available, whether vendors are being paid on time, how claims are affecting cash flow, and where additional resources may be needed to keep the work moving at a steady pace.
Advantages of an Efficient Insurance Back Office
Whether an insurance company is wrestling with a catastrophic weather event that causes a surge in claims or complex new legislation that muddies the regulatory waters, an efficient back office allows the business to adapt quickly and keep costs under control. A sound back office promotes these benefits:
- Resiliency and efficiency: Picture the morning after a hurricane makes landfall. Some insurers will struggle under a flood of claims that puts them behind for weeks. But those with efficient back-office operations can scale quickly, route work automatically, keep policyholders informed, and maintain service without sacrificing speed or accuracy.
- Risk management: The sooner insurers recognize and respond to potential risks, the fewer expenses they incur. An insurer with strong back-office processes can help identify suspicious claims, underwriting inconsistencies, compliance gaps, and potential catastrophes. This allows companies to intervene before risks eat into the company’s bottom line.
- Error reduction: A mistyped policy number or duplicate payment may seem to be a minor hassle, but such mistakes can delay claims, trigger compliance issues, frustrate customers, and force employees to spend hours untangling problems that could have been avoided. By leaning on automated systems that eliminate manual handoffs and duplicated data entry, companies can catch errors earlier, saving time and avoiding headaches that could jeopardize customer trust.
- Compliance: With insurance regulations changing frequently, well-run back offices help insurers remain compliant by revising standard documents, maintaining automated audit trails, and making sure all required steps are followed consistently. This helps demonstrate compliance during audits and regulatory reviews.
- Customer satisfaction: Back-office performance is a fundamental factor that determines whether customers stick around for the long haul. Fast claims processing, competitive pricing on policy updates, and timely responses to billing questions create smoother customer experiences that build trust and strengthen loyalty.
- Scalability: When a hurricane generates thousands of property claims, an influx of auto accidents follows a severe winter storm, or open enrollment drives a surge in policy changes, insurers may find themselves suddenly overwhelmed by questions and requests. A smoothly running back-office helps companies handle spikes in claims and policy changes without forcing employees into months of overtime or leaving customers waiting too long for answers.
- Insights and decision-making: When information related to claims, payments, customer interactions, and policy changes is connected, rather than trapped, in separate systems, insurers gain a clearer view of the business and its imminent risks. This information yields insights that allow insurance companies to identify potential fraud earlier, make well-informed pricing decisions, anticipate operational bottlenecks, and prepare for spikes in demand.
3 Insurance Back-Office Best Practices
In general, companies see the biggest gains in their back-office operations by focusing on the processes that create the most significant delays, spur the most duplicated work, or cause the most customer frustration. These three steps can help insurers get on the right track.
-
Identify and Automate High-Volume Processes
It may be tempting to automate every back-office task to really turbocharge workflow speed. But that might be overdoing it, especially at first. A smarter practice is to start small by focusing on a handful of repetitive processes that employees perform dozens or even hundreds of times each week, such as policy renewals, premium payment reconciliations, taking claims, or requesting missing documentation. Prioritizing high-volume work for finance automation sets up a company for the fastest payoff and gives employees more time to resolve complex claims, assist customers, and make calls that require human judgment.
-
Improve Scalability Through Workflow Standardization
Different branches of the same insurer—or even different adjusters—may handle tasks in completely different ways. That inconsistency can slow down a company when workloads increase. Standardizing workflows makes everyone in the company follow the same process, whether the action occurs in Boston or Phoenix or is done by a new recruit or a veteran employee. Creating standard, shared workflows simplifies staff training, performance measurement, and the ability to temporarily shift work from one office to another if a particular region becomes overwhelmed.
-
Upgrade Your Software Stack
Before investing in new technology, map out the places where work slows down or information gets re-entered multiple times. The best software stack is one that allows information to move seamlessly throughout an organization, giving employees a single, accurate view of every customer and claim. That kind of connected foundation eases deployment of AI and AI agents and improves reporting, strengthens compliance, reduces duplicated work, and gives managers better visibility into day-to-day operations.
Centralize Back-Office Operations With NetSuite ERP
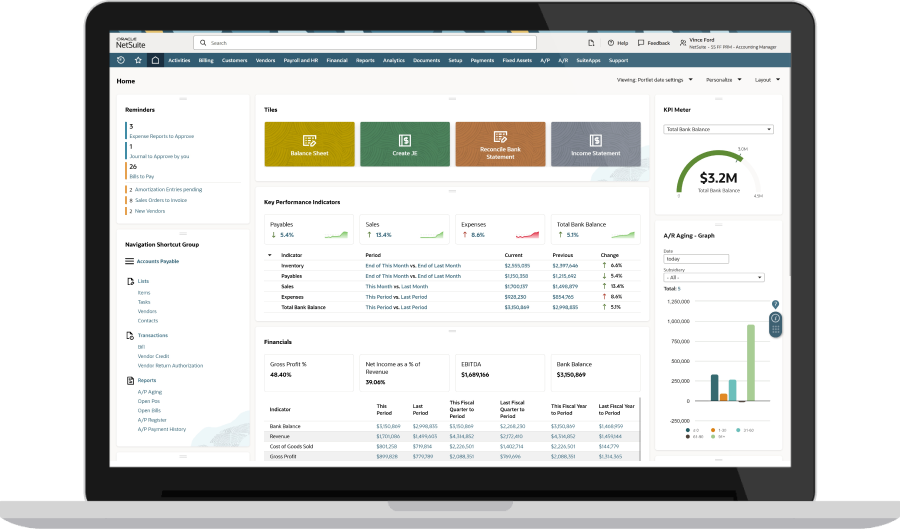
As insurers add new digital tools over time, many end up with software chaos—a suite of disconnected applications meant to manage policy administration, claims, finance, billing, and other core functions. This leads to duplicated work, fragmented reporting, and operational blind spots that confound back-office teams trying to maintain the accuracy of information and keep work flowing smoothly. NetSuite Insurance ERP brings key business functions together on a single, cloud-based platform, giving insurers a unified view of financial and operational performance. That connected data foundation also makes it easier to apply AI in practical ways. ML-driven anomaly detection can spot claim irregularities or compliance gaps because it’s working from consistent, unified records. Automated workflows route tasks on the basis of rules and exceptions, and real-time reporting gives managers visibility into bottlenecks before they can delay operations. Back-office teams spend less time reconciling information among systems, so they are able to respond more quickly to changing business demands, meet customer needs, and stay a step ahead of the competition.
Policyholders may never interact with an insurance company’s back-office team, but those employees influence a variety of customer experiences, such as purchasing a policy or receiving a claims payment. As insurers navigate challenges like staffing shortages and regulatory changes, the back office is evolving from its traditional role as an administrative support function into being a strategic business enabler. To stay ahead of industry pressures, insurance companies are reconfiguring workflows, connecting data, and equipping employees with the necessary tools to deliver the fast, accurate service that retains customers over the long haul.
Insurance Back Office FAQs
What is a back office in insurance?
The insurance back office consists of the administrative and operational procedures performed by software systems and employees who run insurance functions behind the scenes. These employees assist with a variety of tasks, such as processing claims, administering policies, supporting underwriting, managing finances, and maintaining regulatory compliance.
What are common insurance back-office challenges?
Insurance back offices struggle with disconnected data, repetitive manual work, and legacy systems that slow down daily operations and increase the risk of errors. At the same time, insurers must keep pace with changing regulations, unexpected surges in claims, and workforce shortages that challenge scaling operations and the preservation of fast, accurate service.
What is back-office outsourcing?
Back-office outsourcing involves hiring a third-party provider to handle administrative functions, such as claims processing, policy administration, billing, or customer support.