For most of the last 30 years, a bank’s back-office finance systems could be, for lack of a better term, boring, and nobody minded. As long as the general ledger and reports handed to examiners worked, nobody asked hard questions. But that’s no longer true. New reporting requirements and stricter oversight rules have exposed how much those old systems can’t do, and banks don’t have the luxury of finding out the hard way.
Enterprise resource planning software is what replaces them. ERP software pulls a bank’s financial, operational, and risk data into a unified system of record, so, for example, a loan officer and a compliance analyst are looking at the same numbers. This article explains what ERP software does and how to choose the right one for your bank.
What Is ERP in the Banking Industry?
ERP in the banking industry refers to software that runs a bank’s core back-office functions, such as accounting, treasury, procurement, and human resources, while adding the regulatory and risk-reporting capabilities banks specifically require.
Those capabilities include capital-adequacy calculations and audit-ready regulatory reporting, along with anti-money-laundering (AML) and know-your-customer (KYC) monitoring, features that set banking ERP systems apart from the generic platforms used in other industries.
Key Takeaways
- Core banking systems run customer transactions; ERP systems run the bank’s own accounting, payments, payroll, and reporting, and the two systems need to stay in sync.
- Banks no longer get to set their own timeline for upgrading ERP systems; regulatory deadlines are pushing some banks to upgrade systems sooner than they’d like.
- The cloud-versus-on-premises choice comes down to where a bank wants to carry risk, not just the cost.
- Vendor selection often comes down to unglamorous capabilities, like multi-entity consolidation, more than the AI features presented in the demo.
- Most ERP failures in banking trace back to governance and data quality, not the software itself.
ERP in the Banking Industry Explained
A banking ERP system consists of a set of connected modules that cover everything from accounting to compliance reporting. It works off a shared database, with the general ledger at the center. While core banking systems record deposits, withdrawals, and loan activity, the ERP system takes that data and runs accounting, vendor payments, payroll, and the statements and disclosures that boards and auditors expect. The two systems used to operate in silos, but more institutions have narrowed that divide over the past decade by connecting them through APIs so operational and financial data increasingly reconcile automatically.
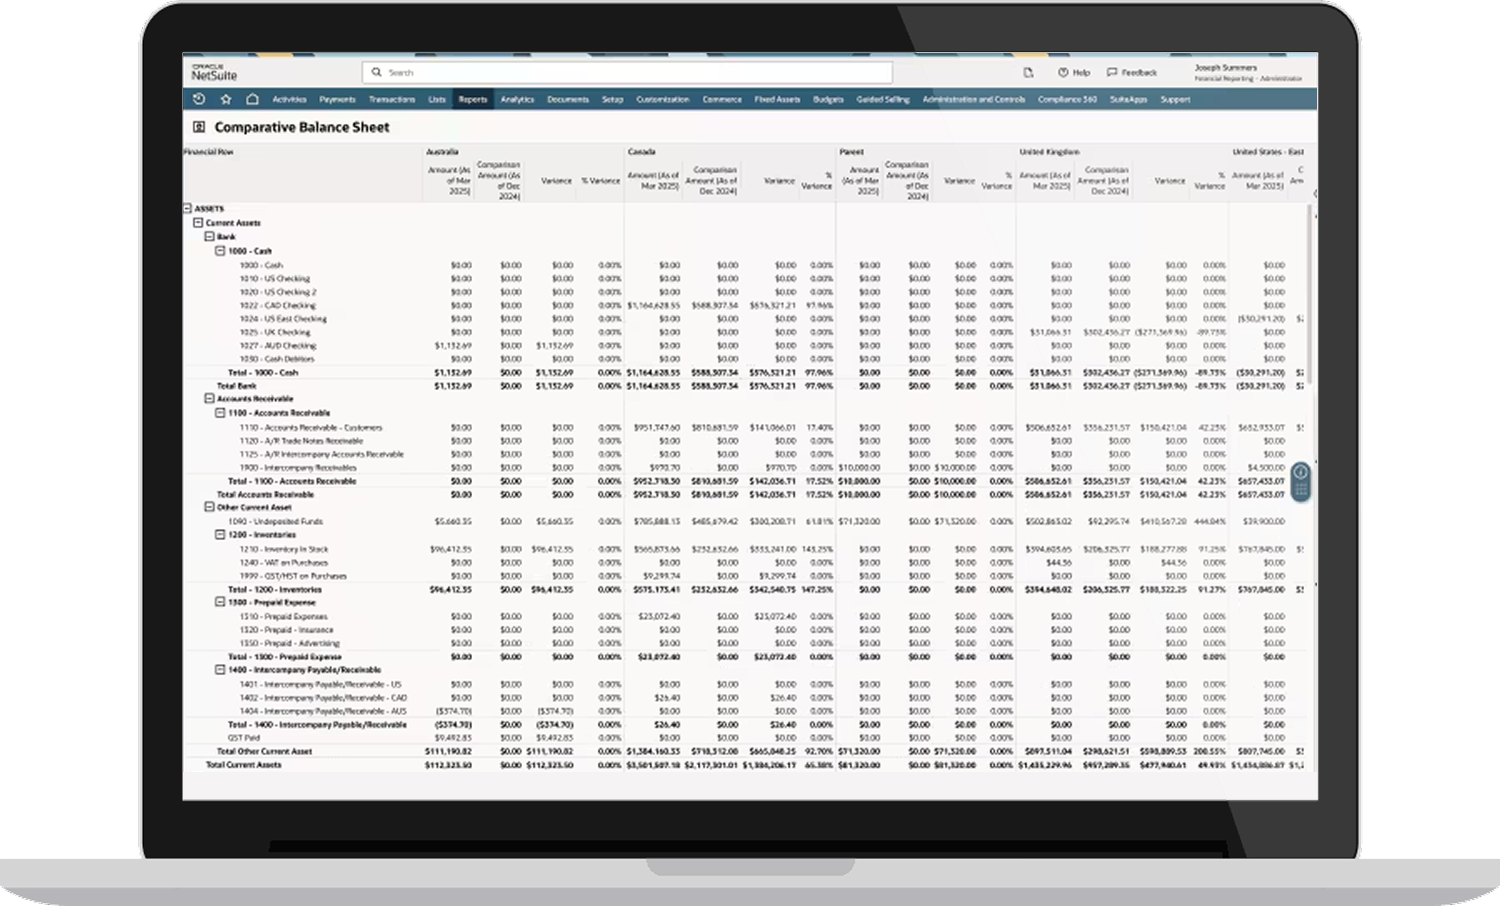
Banking-specific ERP platforms also handle issues that other types of businesses don’t face, such as multi-entity, cross-border transactions and their complex compliance requirements. For example, a single loan might book to a UK entity but draw funding from a parent in the US, and a transaction might open in dollars and settle in pounds. A capable ERP system reports each legal entity separately for local regulators while consolidating everything at the group level. It strips out intercompany transactions along the way, without losing the audit trail.
Why Are Banks Implementing ERP Software?
Data volumes keep climbing, customers expect more, competitors move faster, and regulators ask harder questions every year. Together, that’s enough to make ERP systems close to mandatory for many banks. Start with the data: Spreadsheets and disparate systems that typically handle transactional and customer data have buckled under the load, leading to errors and reconciliation logjams. Customers pile on the pressure as they seek the same level of instant access and personalized experiences from their bank as they get from tech companies, pushing banks to provide a unified view of accounts and interactions. Competition adds another dimension: Digital-first fintechs and neobanks run at a fraction of a traditional bank’s cost structure, forcing incumbents to catch up or lose ground. Regulations compound the situation, as reporting gets more demanding every year and manual processes struggle to keep pace.
New deadlines contribute to the stress. The global cutover to the ISO 20022 payments-messaging standard already happened in November 2025, and it’s a literal requirement. Any bank that can’t send or receive the new message format can’t process certain cross-border payments at all. Banks with European operations now face a second deadline with the EU’s DORA, which requires proof that a bank’s systems can withstand disruption and report incidents properly. For a bank whose systems can’t produce that proof, the practical fix is likely replacing the system that couldn’t clear the bar.
Benefits of ERP Software in Banking
An ERP system’s real payoff comes from how its pieces work together. Tighter controls result in faster reporting, and centralized data means an improvement in one area carries into others. That allows ERP software to deliver the following advantages to banks:
- Optimized operational costs: ERP software captures a transaction once and flows its data into every downstream ledger and report to eliminate duplicated data entry and manual reconciliation. That cuts the time and head count needed to close the books each month.
- Increased productivity: When processes are consolidated on one platform, staff can stop switching between multiple systems with conflicting data. Automated loan approvals and invoice processing free teams from data entry so they can spend more time reviewing loans and vendors.
- Enhanced security: The average data breach now costs $4.99 million, with financial services among the hardest-hit industries. ERP systems protect some of a bank’s most sensitive data with layered defenses. Strong authentication and encryption of data at rest and in transit cover the basics, and continuous monitoring catches threats as they emerge. Advanced safeguards, such as hardware-based protection for cryptographic keys, defend against both external intrusion and insider risk.
- Improved collaboration: Finance, risk, treasury, and compliance teams work from the same, automatically updated numbers—no more waiting on reports compiled by hand.
- Better service delivery: A unified view of customer accounts and history means a call center rep can see a credit card and an open dispute on one screen instead of two, so they can answer questions faster. Integrated payment modules also speed up transfers and payments.
- Strengthened compliance: Automated workflows and monitoring help banks catch regulatory issues early enough to avoid violations, with built-in audit trails ready when examiners request them. This also supports compliance with standards such as GDPR and PCI DSS.
8 Essential ERP Features for the Banking Industry
Some ERP modules handle the everyday mechanics of running the books. Others exist so a bank can answer an examiner’s question in minutes instead of days. The right mix of these features helps banks close faster and handle audits with fewer surprises.
-
Expense Management
Banking ERP systems automate the way employee and departmental spending gets submitted and approved. For a bank with a large branch network or relationship managers submitting client-entertainment expenses, this replaces paper receipts and manual reviews with an electronic workflow that can highlight spending relative to gift and entertainment limits, for example. Approved expenses post straight to the general ledger to cut administrative work and limit data-entry errors.
-
General Ledger Management
With banking ERP solutions, when subsidiary ledgers, such as accounts payable and receivable, post straight to a general ledger, the trial balance refreshes automatically. Finance teams can then use a high-level dashboard to drill down to any single transaction in seconds. A strong banking ERP system also tags each transaction with details, such as department, business line, legal entity, and cost center. That means a bank can view the same rent expense broken out by department or entity, without creating a separate account for every combination, along the lines of “Rent, Retail Banking, UK Entity.” This is especially useful for banks operating multiple business lines and legal entities, where staff might need to view the same expense in several different ways.
-
Accounts Payable and Accounts Receivable
With accounts payable, banking ERP systems automate invoice processing and three-way matching, then reconcile the results against the general ledger. For accounts receivable, it matches incoming payments, such as custody or correspondent banking fees from other institutions, to open invoices as payments come in. Automating both sides speeds up collections and reduces the manual errors that inevitably appear when these processes run on spreadsheets. It also builds trust with vendors and counterparties, who get paid the right amounts on time and receive accurate invoices.
-
Risk Management and Internal Controls
Banking ERP systems extend risk management into credit, liquidity, and market risk, in addition to monitoring fraud, by pairing transaction data with rule-based, and increasingly AI-driven, analytics that pinpoint suspicious activity for review. This capability works alongside internal controls that regulators expect, such as documented policies and defined escalation paths. Guidance provided by the Federal Financial Institutions Examination Council’s Bank Secrecy Act (BSA)/AML manual, for example, expects controls to reflect a bank’s own risk assessment and hold steady despite staff turnover. That’s far easier to demonstrate when the pertinent information is located in one system of record.
-
Reporting and Data Analytics
An ERP system’s real-time, role-based dashboards present tailored views of the balance sheets and income statements that finance teams need every period. ERP solutions also feature predictive analytics that models various scenarios for planning. For example, a treasurer might watch cash positions update throughout the day, while a finance leader pulls a balance sheet as needed instead of waiting for someone to build it. The solution creates the audit-ready outputs that regulators require, too, such as capital-adequacy reports or the transaction detail behind a suspicious-activity filing.
-
Human Capital Management
Some ERP platforms include human capital management (HCM) natively, while other vendors prefer to integrate with a dedicated best-of-breed system. In either case, HCM covers the full employee lifecycle—core HR records, payroll, benefits, performance, and workforce planning. Connecting HCM to the financial core is important for banks because labor is typically the largest operating expense. Combining workforce and financial data allows a bank to weigh staffing against branch performance and plan headcount based on projected transaction volumes.
-
Tax Management
Calculating tax obligations gets complicated fast for banks that operate in several countries, which involves calculating and filing taxes separately for each legal entity and under each jurisdiction’s own rules, even if those entities’ results are combined into one consolidated group view. A banking ERP solution applies the right tax treatment entity by entity while keeping the numbers reconciled at the group level, with documentation ready if an auditor asks. The same automation tracks effective tax rate and on-time filing as metrics to avert the penalties that could arise from committing manual calculation errors.
-
Automation and AI Capabilities
In 2025, 77% of banks had launched or soft-launched generative AI applications, up from 61% in 2023, according to an EY-Parthenon survey. Increasingly, AI capabilities live in the ERP itself, rather than being bolted on separately. Case in point: AI-based document scanning reads and validates invoice data, while machine learning models spot fraud faster than static rules can. The same models can also help forecast cash positions and detect anomalous vendor payments before they cause shortfalls, so staff have time to act. GenAI assistants help answer operational questions and draft reports from plain-language prompts. These gains depend on the data underneath: AI helps most when the ledger is already clean and well governed—but it can amplify existing data problems when it isn’t.
Cloud vs. On-Premises ERP: Which Does Your Bank Need?
For a bank, the cloud-or-on-premises choice comes down to where it wants to carry risk: with a vendor or in-house. Cloud ERP solutions lower up-front costs and speed deployment to help banks scale with growth. Cloud providers also invest in security infrastructure at a level few individual banks can match on their own. On-premises ERP software trades these cloud advantages for direct control over patching, data custody, performance, and customization.
Because banking is so heavily regulated, on-premises ERP systems have long been the default option, which has given banks control over exactly where sensitive data lived and who could access it. That picture is shifting, however. Cloud providers have attained certifications like SOC 1 and SOC 2, along with industry-specific frameworks, that earn trust from regulated institutions. Many large banks now run a hybrid model, keeping core financials in a private cloud and running less-sensitive functions in the public cloud.
A bank’s regulatory regime and data-residency rules, total cost of ownership (TCO) over a realistic five-to-seven-year horizon, scalability needs, and in-house IT capabilities all factor in, as well. So does the number of third-party systems the ERP system has to connect to, given that a single, connected suite means fewer integration points to secure than a best-of-breed mix linked by APIs.
Selecting the Right ERP Software: 5 Tips for the Banking Sector
A poor ERP fit doesn’t show up in a demo. It shows up two years later, when the vendor’s roadmap stalls or a promised feature never sees the light of day. Getting an ERP evaluation wrong squanders the budget, stalls implementations, and creates compliance issues that take years to untangle. These five tips catch mismatches early:
- Look for vendors with industry-specific experience: A vendor that already understands banking’s specialized needs, such as multi-entity consolidation and capital reporting, is far better equipped to meet them than a generalist. Their experience also lowers costs, because those capabilities are built into the platform and don’t entail expensive custom development.
- Understand your TCO: License or subscription fees are only part of what a bank spends on ERP software. A rigorous TCO analysis should account for implementation, training, maintenance, customization, and—for on-premises deployments—hardware. These should be evaluated over a multiyear payback period.
- Determine what your integration needs are: ERP software must connect to core banking, payment, CRM, AML/KYC, and treasury systems. Map those requirements before evaluating vendors and test them with a proof-of-concept on real data.
- Ask for customer references: Vendors naturally steer banks toward their most satisfied customers, but those referrals don’t tell the whole story. Dig further by reading independent reviews and talking with institutions of similar size and regulatory footprint. Ask the staff running the system what implementation was really like.
- Evaluate security and compliance capabilities: Verify that the vendor offers required security capabilities and holds current certifications, such as SOC 1 and SOC 2. Check that its built-in compliance tools map to the regulators the bank answers to, such as Basel, BSA/AML, GDPR, and MiFID II.
Troubleshooting 3 Major ERP Implementation Challenges in Banking
The costliest ERP failures in banking tend to have less to do with the software itself than with how well the switch is executed. A major European bank found this out the hard way in 2018: A botched core migration disrupted banking for millions of customers, and regulators fined the bank more than £48 million, not because the technology was at fault, but because the program itself was poorly governed and its third-party risk wasn’t managed. Implementation risk shows up most often in the following three places.
-
Data Migration
Banks hold millions of customer records containing years of transaction history—but those records are likely to be spread across multiple systems that were never meant to work together. Old data rarely fits a new system cleanly because legacy platforms store information in custom fields and hierarchies that have no direct ERP equivalent. But every record has to be mapped, with duplicates and errors eliminated. The solution is to treat migration as its own project with dedicated governance. To do that, assess and clean the data up front, then map each legacy field to the new system and validate the results before cutover. Staging the migration so old and new systems initially run in parallel, and preserving the ability to roll back, contains the risk that a single cutover can’t guarantee.
-
Cost Management
ERP projects have a reputation for going over budget once work begins, and banking implementations are especially prone because of the customizations they require. Additional culprits include underestimated consulting and training costs. The most effective defense is a realistic, padded budget built from a TCO analysis, not the initial license quote. Negotiating a clear, itemized scope up front and rolling out the migration in phases can help contain overruns.
-
Integration With Legacy Systems
Banking platforms often store data in proprietary or mainframe formats with no up-to-date APIs, which complicates ERP integration. Left unaddressed, this oversight re-creates the silos the ERP solution was meant to remove. It also introduces operational risk at cutover, when downtime can disrupt payments or payroll. A hybrid integration model tends to work better than a wholesale replacement. Migrate high-value functions, such as core financials, first, then use middleware or an API layer to sync up legacy systems until they can be retired.
Modern, Reliable ERP Software With NetSuite
Disconnected systems and manual work leave banks with data that never quite matches up. NetSuite ERP Software for Financial Services overcomes that challenge by bringing finance, operations, risk, and compliance into a single solution. As a result, a transaction recorded once automatically appears in every system that requires it. Automation is another NetSuite strength. AI agents can monitor financial close continuously to highlight exceptions and propose immediate fixes. The same AI can turn a quarter’s financial data into plain-language narratives for stakeholders, cutting the hours analysts otherwise spend writing explanations to go with the numbers.
NetSuite Multi-Entity Management
Clean data, a realistic budget, and tested integrations before go-live help prevent ERP implementation failure, and they’re what make an ERP system worth the investment. When banks skip any of those three factors, they’re doing more than avoiding the necessary work: They’re effectively scheduling the same rebuild for a few years from now, probably under a different vendor’s name.
ERP in the Banking Industry FAQs
How does ERP software affect regulatory compliance in banking?
ERP software strengthens regulatory compliance in banking by automating report generation and capturing time-stamped audit trails. It also integrates anti-money laundering and know-your-customer screening directly into everyday workflows.
Which teams benefit from ERP software?
ERP software benefits nearly every function in a bank, including finance, risk, treasury, operations, HR, procurement, IT, and customer-facing efforts. The benefits include a faster month-end close and a fuller view of the customer relationship.
How does ERP software support digital transformation in the banking sector?
ERP software supports digital transformation in the banking sector by providing the clean, real-time data that every other initiative, such as AI risk analytics and embedded finance, depends on to work.