Wealth managers know things about their longtime clients that don’t show up in financial statements—for example, which spouse makes the big financial decisions, or which stocks can’t be sold for sentimental reasons. When an advisor leaves a firm, they take that institutional knowledge with them, and the client relationship suffers. That’s particularly important in light of recent trends. Cerulli Associates projects $124 trillion will pass to heirs and charities through 2048, but only 20% of heirs who received their inheritance said they expect to remain with their current advisor.
A CRM system built for wealth management holds that knowledge in one place and puts it to work across an entire practice. This article explains what these systems do and how firms can choose the best fit.
What Is CRM for Wealth Management?
CRM for wealth management is software that helps advisory firms record and act on every detail of their client accounts. It’s built to manage long-term financial relationships and the advisory’s regulatory obligations, unlike general-purpose CRM tools, which focus on sales pipelines.
Key Takeaways
- A wealth management CRM organizes information pertaining to a client’s family members, trusts, and accounts.
- Fewer advisors to serve a growing, more demanding client base, combined with stricter SEC and Financial Industry Regulatory Authority (FINRA) rules, are pushing firms toward CRM systems that save time and maintain audit-ready records.
- Analytics and reporting help advisors provide more personalized service as firms align their resources with the value of each individual client.
- AI is increasingly built into CRM systems to draft client reviews, highlight portfolio and compliance exceptions, and give advisors a jump-start on tasks they’d usually do manually.
Wealth Management CRM Software Explained
The wealth management business runs on relationships, but the information that firms need about each client accumulates faster than manual processes can capture it. A wealth management CRM creates and maintains up-to-date records for every account, so it becomes the de facto home for institutional knowledge.
At the center of the system sits the household—a record that groups related individuals, such as spouses and dependents, with their trusts and accounts, as well as the financial planning and compliance obligations tied to each. The CRM provides a communications log that captures each household’s calls, emails, and meeting notes, and also serves as document storage for signed agreements and financial plans.
How Does Wealth Management CRM Software Work?
The clearest way to understand a wealth management CRM is to follow a client through it. A prospect enters the system as a lead and moves through defined qualification and discovery stages before receiving a proposal. Workflow automation prompts the advisor and support staff for next steps along the way. Many systems now use AI to draft follow-up emails and summarize discovery meetings, including details drawn from the record.
When the prospect signs on, the CRM guides onboarding with electronic forms and e-signature paperwork. Automated Know Your Customer (KYC) and anti-money laundering (AML) checks are also performed. From there, the software pulls in data from the firm’s other tools, such as custodians and financial planning software, so advisors don’t have to manually re-enter it. Throughout the ongoing relationship, the system logs each meaningful interaction and supports recurring work, such as scheduled portfolio reviews. The system reminds advisors to reach out to clients about important life events. The CRM also preserves interactions in tamper-proof form for regulators and routes potentially sensitive communications for supervisory review. Analytics then draws on the same underlying data to show advisors and leadership where the practice stands.
Why CRM Software Is Essential for Wealth Management Firms
Approximately 35% of all financial advisors, who manage 40% of industry assets, plan to retire within the next 10 years, and more than one-quarter of them express uncertainty about their succession plans. If that scenario plays out, the remaining professionals will be responsible for more clients, leaving less time to serve each one well. Much of their time already disappears into administrative work, such as logging interactions and chasing compliance documents, which makes it tough to meet rising client and regulatory expectations.
Investors also want personalized service, like timely advice about a child’s tuition bill or an approaching inheritance, but advisors can deliver it only when they know each household’s details well. But those details can get lost without a unified system of record. Meanwhile, the SEC and FINRA expect firms to preserve client communications. Firms also have to supervise account activity and produce records on demand. Manual recordkeeping simply can’t handle all the weight as firms grow.
A CRM built for wealth management addresses these issues. It lowers the administrative burden on advisors and maintains shared, up-to-date records so all team members can offer informed service. It also supports compliance by automatically archiving and time-stamping all emails and logged calls to create the audit trail regulators want. Newer platforms do even more. For example, AI agents can assemble client reviews by pulling portfolio performance and noting any changes since the last meeting. They can then draft talking points that an advisor can review and approve before the next meeting.
7 Key Wealth Management CRM Features
The features of a wealth management CRM all serve one goal: keeping a complete and current record of every client relationship and acting on it consistently. The following key features build on each other:
Client Management
The CRM holds all client contact details, so an advisor can open a single record and see the full arc of a client’s financial life. More advanced systems apply AI to that data to pinpoint issues a client should know about—an approaching required-minimum-distribution age, for instance, or an allocation that’s drifted off target.
Unified Contact Management
Household mapping links spouses, dependents, trusts, family businesses, and outside professionals, such as a client’s attorney or accountant, into a single view. Estate and tax decisions usually hinge on a spouse’s assets or a trust’s terms, and without a system that connects people and accounts, advisors would have to piece together the full picture by hand—slow work that invites mistakes. The most advanced platforms automatically update these connections and identify new business opportunities. For example, the system might point out that a client’s accountant also advises a prospect the firm has been trying to reach.
Compliance Management
Wealth managers work under recordkeeping rules that most businesses never encounter. In the US, the SEC and FINRA require that client communications and business records be preserved for years in complete, tamper-proof form—commonly in write-once, read-many (WORM) storage that can’t be altered after the fact. Firms also must actively review communications and account activity, and document that those reviews took place. The cost of noncompliance is high. In 2024, the SEC ordered 11 firms to pay more than $88 million for failing to preserve required electronic communications. Enforcement of these requirements is shifting, however. The SEC has moved its focus to fraud cases, but FINRA continues to pursue recordkeeping failures directly. Regulators have also begun to apply these principles to AI, with firms now expected to inventory AI’s actions and maintain human oversight of its decisions. A CRM built with these requirements in mind handles much of this work automatically and highlights actions—sending a client-facing email or updating an account, for example—for supervision.
Workflow Automation
Workflow automation runs repeatable processes (think: annual review cycle and beneficiary changes) that improve customer service and compliance. Automations can include everything from basic triggers—such as creating an onboarding checklist once a new client signs an investment advisory agreement—to AI that drafts follow-up messages and recommends next steps. Newer systems also use AI agents to perform those next steps themselves.
Mobile Access
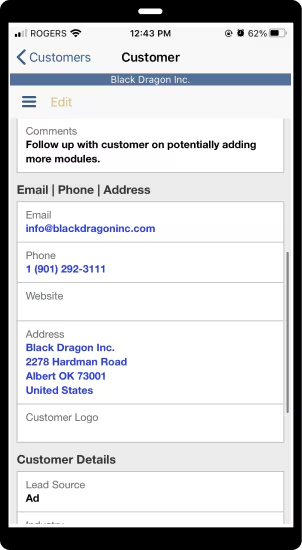
Advisors spend much of their time away from a desk—in a client’s home or at an airport, for example. Mobile access lets them do real work from a phone or tablet, such as reviewing a household’s details before a meeting or logging a call right afterward. A note captured in the moment, rather than hours later back at the office, keeps the client record accurate and up to date. Some systems also let advisors call a client directly from the app, without switching between tools. The next step for some providers is building CRM functionality directly into the messaging and scheduling tools advisors already use, so pulling up a client’s record won’t require a separate app.
Integration Support
A CRM’s value depends heavily on how it works with a firm’s other tools—gathering holdings from custodians, sharing plans and goal data with financial planning software, pulling performance figures from portfolio-reporting systems, and handling paperwork through e-signature tools. Strong integration keeps the household record accurate without staff having to enter data in multiple places. This typically requires two-way, real-time integration; a one-way export that‘s limited to pushing data out won’t qualify. Integration quality, more than any single feature, frequently determines whether advisors are happy with their technology overall, because even the best individual tools lose their luster when they don’t share clean data.
Analytics and Reporting
Analytics and reporting help advisors and the firm’s leaders act on CRM data. At the client level, they can review portfolio performance and confirm that scheduled reviews get done. They can also track a household’s progress toward its financial goals. At the practice level, they can use the CRM’s dashboards to monitor assets under management by advisor, gauge pipeline value, measure review-completion rates across the book, spot where onboarding is slowing down, and track other key performance indicators. Meanwhile, the CRM segments clients into tiers according to assets, complexity, life stage, or engagement level and keeps those tiers current as account data changes. This helps wealth managers provide customized service and helps firms assign resources based on each relationship’s value.
Advantages of Using a Wealth Management CRM
With a wealth management CRM, work that once relied on manual effort and individual memory now runs through a shared system. That gives advisors time to strengthen client relationships. In turn, those relationships fuel growth. A practice run on spreadsheets and inboxes can hold it together for a while, but these are the benefits it leaves on the table:
- Faster onboarding: Digital forms and e-signature tools cut down on most paperwork delays. Automated KYC and AML checks can shrink account opening times from weeks to days or even hours.
- Lowered administrative burden: Automated data entry and scheduling give advisors hours each week for client-facing work.
- Strengthened client relationships: A single household record means commitments don’t slip away and clients aren’t forced to re-explain details the firm should already have on file. It also lets relationships survive an advisor’s departure with their history intact.
- Efficiency enhancements: An advisor can pull up a household’s full history in seconds. Centralized data and standardized processes help firms avoid the rework that can pile up when staff track clients in various ways.
- Growth and scalability: Firms can add clients and staff without needing to increase overhead because the system absorbs much of the ongoing administrative work, such as scheduling reviews and sending follow-ups.
Selecting the Right Wealth Management CRM for Your Firm: 4 Tips for Getting Started
A wealth management CRM is a long-term commitment because implementation takes time, and switching later requires data migration and staff retraining. The goal is to choose a system that matches how each firm works. Defining CRM requirements with input from advisors, operations, compliance, and IT is a sound place to begin. These four tips can focus the search:
- Identify current bottlenecks: Find where your processes currently break down—perhaps onboarding stalls at document collection or client requests get lost because there’s no tracking system. Build demo scenarios to test whether a platform solves these problems.
- Factor scalability into your vendor search: A CRM that fits your needs at first can fall short as you add advisors and new services, such as tax planning or estate and trust work. Most cloud-based systems can handle more users, but tools built for a small practice may lack the permissions and governance controls advanced teams need. They may also lack support for the cross-team workflows that keep service and compliance consistent as head count rises.
- Consider how a CRM system fits into your existing tech stack: Inventory the tools your firm relies on now and those it expects to adopt, then test each integration with real data. Confirm how easily your data can be exported to guard against vendor lock-in.
- Plan for adoption, not just selection: A capable CRM that enjoys full adoption will outperform a sophisticated one that wins only partial adoption. To kickstart usage, budget time and resources for data cleanup before migration, as well as hands-on training. Also, plan for an adjustment period after rollout. Temporary dips in productivity are common as teams get used to new workflows.
Your CRM Should Do More Than Store Contacts
Siloed client data and heavy compliance demands stretch advisors too thin at precisely the moment clients need attention. There’s one proven way to solve each of those problems: running the whole practice on a single platform that unites client data, finances, and compliance, and automates the work across them. NetSuite ERP Software for Financial Services brings accounting, procurement, compliance, and reporting capabilities into one suite, with role-based access and audit-ready records built in. NetSuite CRM, a component of that suite, includes a Customer 360 dashboard that allows advisors to build a complete view of each client. Throughout the platform, AI-powered analytics scan client and portfolio data to uncover important trends—say, a household nearing a required distribution age. It also highlights exceptions a busy team might miss, such as a transaction that’s out of character for a client.
Manage Client Relationships on the Go With NetSuite
The knowledge a wealth manager builds over decades—such as what a family really needs and when to reach out before being asked—has also been the hardest thing to replace when an advisor leaves. A CRM built for the industry is what turns that knowledge into a permanent record that lasts long after an advisor departs. That shift is what persuades a client to trust the firm itself, not just the advisor sitting across from them.
CRM for Wealth Management FAQs
What is a CRM system in wealth management?
A CRM system in wealth management is software that gives advisory firms a shared, up-to-date record of each client’s accounts, goals, and interactions. It centers on the household, rather than a single contact, so advisors can get a complete financial picture that includes family members, trusts, business entities, and past communications, all in one place.
How is a wealth management CRM different from a standard CRM?
A wealth management CRM is different from a standard CRM in that it is organized around a continuous, multidecade household relationship and its regulatory obligations. A standard CRM is built around a linear sales pipeline that ends when a deal closes.
What are the key features of a wealth management CRM?
The key features of a wealth management CRM are client management, unified contact management, compliance management, workflow automation, mobile access, integration support, and analytics and reporting. Together, they keep a complete record of each relationship and support a firm’s service and compliance work.